Commercial Loans
Commercial capital that moves when the deal does, from people who have underwritten Arizona property through every cycle since 1992.
- Loan to value
- Up to 80%
- Loan size
- $50K–$25M
- Position
- First deed of trust
- Term
- 6–24 months
- Structure
- Interest only
Pricing is set deal by deal, on the property, the leverage and the plan. Call and we will talk about your numbers.
The building makes sense. Maybe it is the shop next to yours, an off-market industrial bay, or a retail pad the bank cannot price because the rent roll is thin.
Commercial lending at a bank is built for stabilized property with seasoned income. The moment your deal has a story to it, vacancy to fill, work to finish, a seller who will not wait for a loan committee, you stop fitting.
That is the deal we want to see. A decision maker reads it, walks it when it matters, and prices it on the value and the plan. We have financed Arizona commercial property this way since 1992, through every rate environment on record.
Judgment, not category
Banks lend to categories. We underwrite the specific property in front of us: what it is worth today, what it becomes under your plan, and how the loan retires. That is why our book includes restaurants, shop buildings, medical space, and properties no form was ever written for.
Start with a phone call
Call (480) 783-8800 and tell us about the property. You will be talking to a decision maker, and within a few minutes you will know whether the deal works and what the path to closing looks like.
Leverage above is a program range. Every deal is priced on its own fundamentals. This is not a commitment to lend.
What kinds of commercial property do you fund?
Office, retail, industrial, and the specialty properties banks struggle to categorize: restaurants, assisted care, horse property, mixed use. If the value is real and the plan is sound, the category matters less than the deal.
My property sits partly vacant. Will you still lend?
Often, yes. A vacancy problem is usually a story with a plan behind it. We underwrite where the property is going, not just its current rent roll, and we size the loan so the numbers work on the way there.
What does the exit need to look like?
Concrete. A sale, a refinance into permanent financing, or income that retires the debt. We will ask how the loan ends before we talk about how it starts.
“They brought the experience and resources to the table that made everything seamless.”
Mickey C., Kenwood borrower
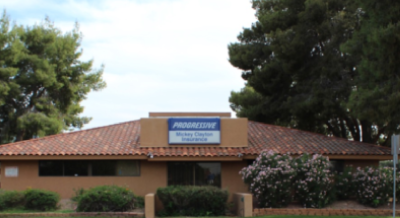
$420,000 Commercial Loan in Phoenix, AZ
“The team at Kenwood Mortgage helped me seize a discount on a time sensitive business opportunity. They brought the expe…
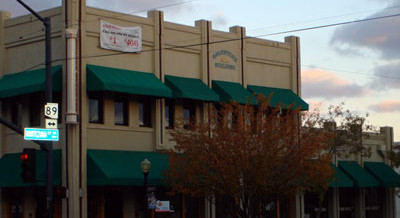
Historic Property in Prescott, AZ
Tenant improvement funds for historic and beautiful Balentine Building “On The Square” in downtown Prescott.